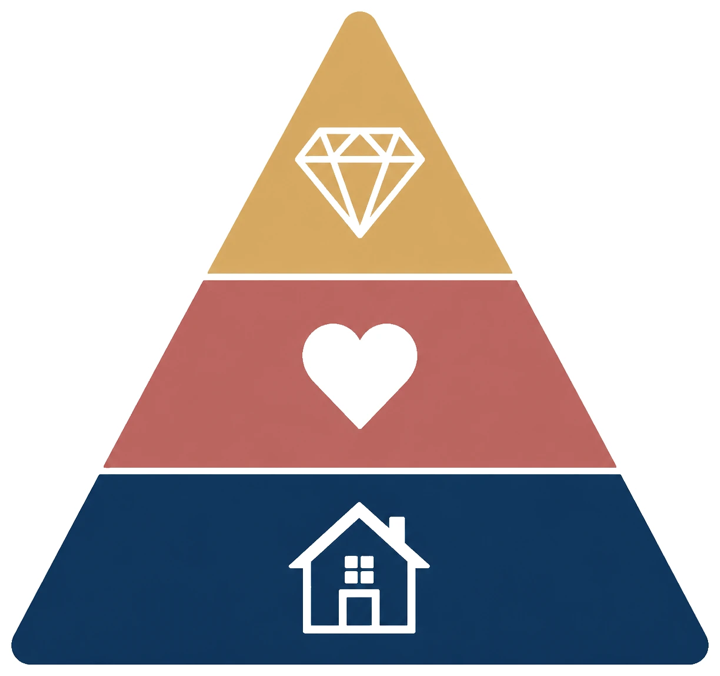
The 3E's of Retirement

Your savings are not the same as your income

Many retirement plans are built around a single number. The 3E's ask a better question: what does your life actually cost, and what kind of money should pay for it?

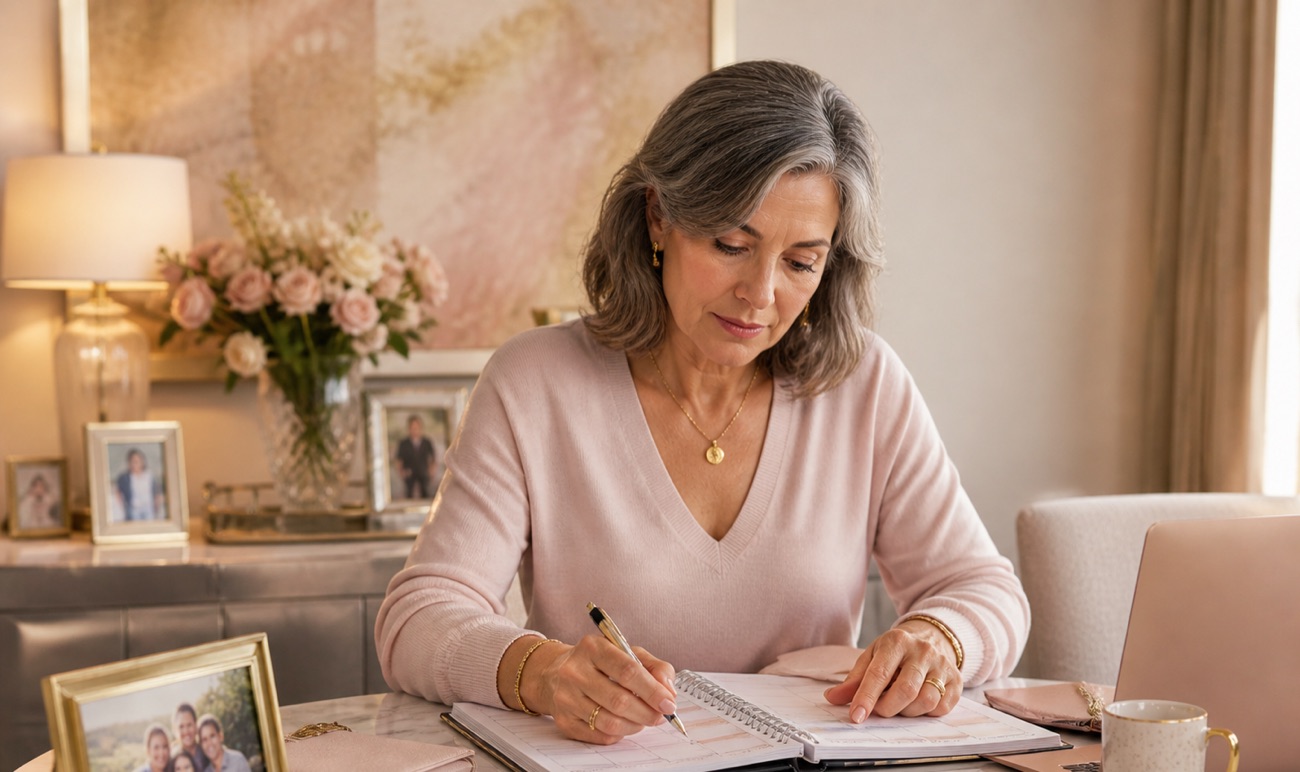
A woman at her kitchen table with a notebook, thinking about retirement

Why many retirement plans miss the point

Many retirement plans are built around a single number. Do you have enough? The number is calculated, the spreadsheet is printed, and the woman walks out feeling either relieved or panicked depending on what the spreadsheet said.

But the spreadsheet doesn't tell her the most important thing. It doesn't tell her whether the income coming out of that money will reliably cover her life, every month, for the next 30 years.

A pile of money is not the same as income. A 5% withdrawal rate looks fine on paper until the year the market drops 25%. Suddenly the same withdrawal is taking 7% of a smaller pile, and the math that worked in the spreadsheet starts to unravel.

Instead of asking how much do I have, the 3E's ask: what does my life actually cost, and what kind of money should pay for it?

The answer is different for each layer.

Layer one · The foundation

Essentials

An Essentials card on a desk with groceries, bills, keys and a calculator
The principle

Essentials should be covered by income you cannot outlive.

Three sources fit this description: Social Security, pensions, and lifetime income annuities. None of them rise and fall with the market. This is the foundation everything else sits on.

The expenses that keep your life running. Housing. Healthcare. Groceries. Utilities. Insurance. Prescriptions. Transportation.

These are the bills that arrive whether the market is up or down. They don't care what the news is doing. They don't care whether your portfolio had a good year. They just need to be paid.

Where many plans fall short

Many retirement projections assume the stock market will cooperate every year for the next 30 years. It won't. When essential expenses depend on market-based withdrawals, a single bad year early in retirement can force hard choices nobody should have to make at 72.

Selling investments at a loss to pay the mortgage. Cutting back on prescriptions to make groceries work. Skipping the dentist to keep the lights on. These are the quiet retirement compromises that nobody wants to talk about, and they happen to women who did everything right.

Layer two · The reward

Enjoyments

An Enjoyments card on a desk
The principle

Ideally, Enjoyments should also be covered by protected income.

When they are, a market drop becomes an inconvenience, not a lifestyle change. You still go to dinner. You still take the trip. You still see the grandkids. The market does what it does, and your life keeps going.

The expenses that make life feel like a life. Streaming services. Dinners out. The gym membership or the golf membership. Weekend trips. Time with grandkids. Hobbies you've waited years to actually enjoy.

These are not luxuries. These are the things that make retirement feel like the reward you earned, not just the years after work ended.

Where many plans fall short

When the market drops, Enjoyments are usually the first thing to get cut. The trip is postponed. The dinner gets cancelled. The gym membership goes. The grandkids' visit gets shorter. The hobby class doesn't get renewed.

That's a quiet kind of grief many retirement projections never account for. The math says you'll be fine. The reality is that you spent a year staying home because the market scared you out of living.

A retirement that pays your bills but takes away your joy is not the retirement you saved for.
Layer three · The dreams

Extravagances

An Extravagances card beside a passport and travel journal
The principle

Extravagances can be funded by a thoughtful mix of protected income and other assets.

The point is to plan for them on purpose, not hope there's something left over at the end. Some Extravagances belong on the protected-income side. Some can ride a little market risk. The right answer depends on your situation, but the planning has to be intentional.

The bucket list. The things you've worked your whole life to enjoy. A family trip to Hawaii with the kids and grandkids. A 50th anniversary celebration. The vacation home you've been talking about for 20 years. The legacy gift to your children. The dream you've been quietly carrying for decades.

These are the things that don't show up on a spreadsheet but show up in every late-night conversation about what retirement was supposed to be for.

Where many plans fall short

Many women never give themselves permission to plan for Extravagances at all. They've spent so many years putting others first, taking care of children, parents, spouses, and careers, that the bucket list feels selfish. Or it gets pushed to "someday." Or it becomes the thing that gets sacrificed when the spreadsheet looks tight.

It isn't selfish. You earned this. And "someday" is not a retirement plan.

Protected income

What does "protected income" actually mean?

Protected income is income you cannot outlive, that doesn't depend on what the market is doing in any given year. There are three sources that fit this definition.

Income you cannot outliveDoesn't depend on the market
What it is

The most reliable income stream most American retirees have.

  • Adjusted for inflation.
  • Paid for life.
  • Backed by the federal government.
Your next stepSee your own Social Security estimateVisit my Social Security at ssa.gov
The big decision
about 75%possible difference in monthly income, claiming at 62 versus 70

The single most important Social Security decision most women make is when to claim, because the difference between claiming at 62 and claiming at 70 can change her monthly income by about 75% for the rest of her life.

If you're married

If you're married, the higher earner's claiming age matters for both of you. The surviving spouse generally keeps the larger of the two benefits, so that one decision can shape the income of whoever lives longer.

What it is

Increasingly rare, but if you have one, it belongs in the protected-income column.

  • Most pensions pay for life.
  • Some have survivor benefits.
  • Some are inflation-adjusted, most are not.
Your next stepHave a pension decision coming up?Talk it through in a free conversation
The big decision

If you have a pension decision coming up, the choice between lump sum and lifetime payments is one of the biggest retirement decisions you'll ever make.

If you're married, the payout option matters for both of you.

Single-life

A single-life option usually pays more each month but can stop when the retiree dies.

Joint-and-survivor

A joint-and-survivor option pays somewhat less so payments can continue to the surviving spouse.

What it is

An annuity is a contract with an insurance company that, when structured for lifetime income, can pay you a set amount every month for as long as you live, however long that turns out to be.

  • The amount isn't tied to market performance.

The guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company.

Your next stepWondering if annuities are “bad”?Read the honest answer in our FAQ
Good to know

Different annuities are designed for different purposes. The right tool depends on what gap you're trying to fill in your 3E's picture.

The trade-offs matter too.

  • Many annuities have surrender periods,
  • some carry fees,
  • and money placed in an annuity is less flexible than money in a savings or brokerage account.

Sometimes an annuity isn't the right fit, and I'll tell you if it isn't yours.

What about your 401(k) and IRAs?

On their own, they aren't protected income, because their value rises and falls with the market. They're often the savings that support your Enjoyments and Extravagances, and part of them can also be used to create more protected income for your Essentials. The quiz and the worksheet help you see which job your savings should do.

Many women in retirement use a combination of these sources. The art is figuring out the right mix for your specific situation.

Why this framework is built for women

Three risks women face that many plans don't account for

Late 80s
how long the average 65-year-old woman can expect to live (SSA estimates)

Women live longer.

The average 65-year-old woman in the United States today can expect to live into her late 80s, according to Social Security Administration estimates. A meaningful percentage will live well into their 90s. That means a woman's retirement income needs to last longer than a man's, often by five to seven years or more.

Longevity is wonderful. It is also expensive.
4 of 5
married women will outlive their husbands

Women are more likely to walk through retirement alone.

Four out of five married women will outlive their husbands. When a woman loses her husband, she typically loses:

  • one Social Security check
  • sometimes a pension
  • and her tax bracket compresses from married-filing-jointly to single

Her income drops at the same time her costs may be rising. Many retirement projections built for couples don't show what happens to her after.

3 places
time away from work shows up later

Women often carried the invisible load.

Many women took time out of the workforce to raise children, care for aging parents, or support a spouse's career. That time shows up later as:

  • smaller Social Security benefits
  • smaller 401(k) balances
  • and fewer years of pension accrual

None of that is a moral failing. It's a structural reality.

The 3E's framework is built around these realities, not in spite of them.

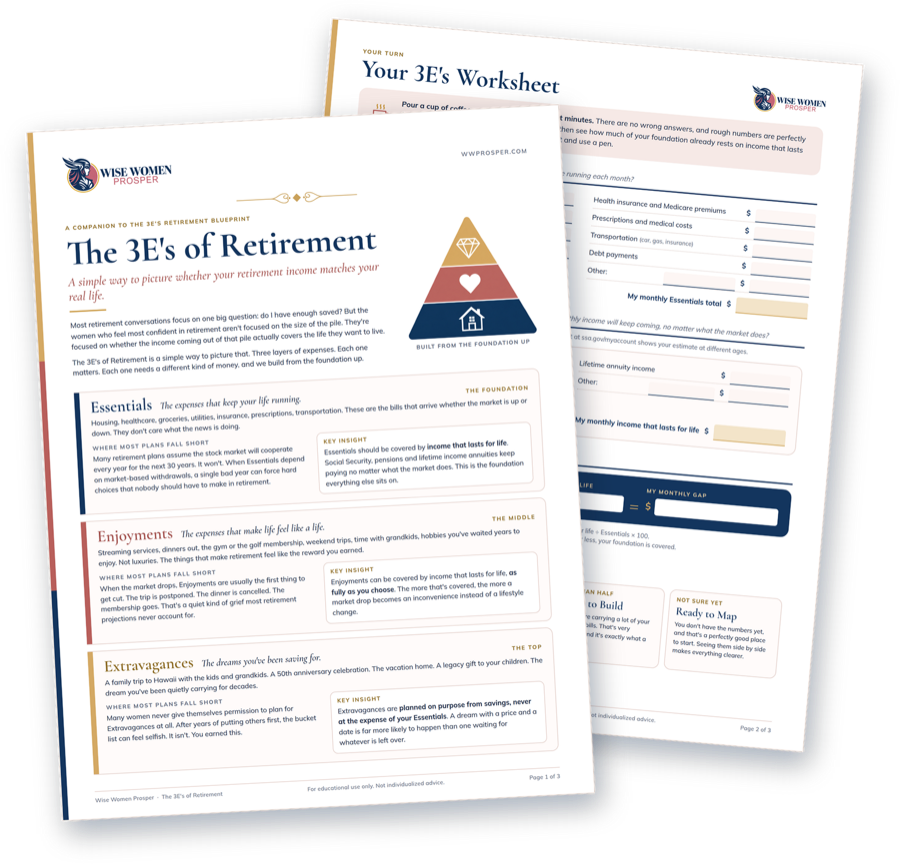
The 3E's Worksheet pages
A free tool for you

See your own 3E's picture on paper

3 pagesAbout 15 minutesType in it or print it

The 3E's make the most sense when you see them in your own numbers. That's what your 3E's worksheet is for.

  1. Page one explains the three layers.
  2. Page two walks you through your Essentials and your income that lasts for life, then shows how much of your foundation is already covered.
  3. Page three is the fun part: your Enjoyments, the dreams you've been saving for, and a note to yourself.

Pour a cup of coffee and give yourself about 15 quiet minutes. Type right into the PDF or print it and use a pen. Rough numbers are perfectly fine. Then bring it to your free conversation with me, finished or not.

A peek at your result
Your 3E's BlueprintHow much of each layer is covered by income that lasts
Essentials80%
Enjoyments45%
Extravagances20%

Sample only. Your own Blueprint is built from your answers.

Ready to see your own picture?

Ten questions, about three minutes, no dollar amounts.

The free conversation is 30 minutes by Zoom or phone, with no obligation. Married? Bring your spouse. You're both welcome.

Wise Women Prosper Smart women save. Wise women prosper.
[email protected] · (928) 582-7661 Mon to Fri, 8:30 a.m. to 5:30 p.m. Arizona time Serving women in Arizona, California and North Carolina · Mailing address: 633 W. 5th Street, Ste 1050, Los Angeles, CA 90071

California Ins. Lic. #4074927 · NPN 17949603 · Licensed in Arizona, California and North Carolina. Wise Women Prosper provides insurance and educational services only. Veronica Aguilera is a licensed insurance agent in California, Arizona and North Carolina. We do not provide investment, tax, or legal advice. Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Annuity product features, fees, and limitations vary by carrier and contract; full details are provided before any purchase. This site is for educational purposes only and does not constitute an offer or solicitation in any state where Wise Women Prosper is not licensed. © 2026 Wise Women Prosper